26th October 2026
This communication is for informational purposes only and does not constitute financial, legal, or professional advice. ACCR does not hold an Australian Financial Services Licence and does not provide financial product advice. The purpose of this communication is not to provide financial product advice. Please read the terms and conditions attached to the use of this site.
This article by Lead Analyst - Oil & Gas, Alex Hillman, was first published by Energy News Bulletin on 21 October 2026.
In the past year, Browse has been pitched as the answer to a West Australian gas shortfall and as backfill for the ageing North West Shelf. Yet more than 50 years after discovery, and after $2.5 billion in development costs, it still hasn’t reached a final investment decision. That usually says something about a project’s viability.
When a project keeps finding new reasons to exist, investors should check whether any of them hold up. In our new analysis, we started with the biggest: does WA actually need the gas?
WA has the gas
As WA shuts down its coal generators, it needs to keep the lights on, and AEMO projects a shortfall from 2030. But when we looked at how much gas is available in WA, we found that there’s plenty. The tightest year is 2035, with a 9.6 million tonne surplus, equivalent to 107% of forecast demand.
That’s without cancelling a single existing LNG contract, and without developing any new gas projects.
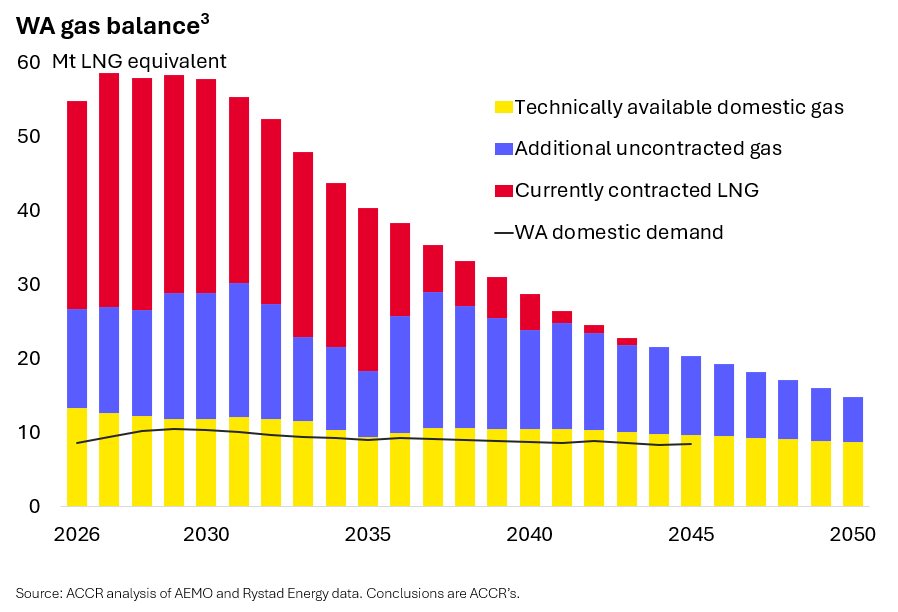
Our analysis doesn’t contradict AEMO. We measured different things. AEMO asked how much gas producers plan to supply to the local market, and found a shortfall. We asked how much gas is available, and found a surplus. Both can be true.
The real constraint is infrastructure. In 2035, the plants that move gas from the LNG facilities into the domestic system have just a 3% buffer. That’s tight. But it’s a delivery limit, and more upstream supply can’t fix it.
The same goes for the North West Shelf. As its own fields decline, it can be backfilled with Scarborough gas through the Pluto–KGP Interconnector, without Browse.
Browse doesn’t stack up
Critics say our analysis ignores the commercial incentives of LNG exporters, and that WA needs Woodside to develop Browse to secure supply.
The problem with that argument is that commercial incentives work against Browse. Because it is so remote and complicated, Browse is more expensive than 70% of competing global gas resources. Building it would sit uncomfortably with Woodside’s claims that it allocates capital in a disciplined manner.
Its history tells the same story. Browse has been through multiple FEED (front-end engineering and design) studies and received key government approvals twice, and it still hasn’t been developed. In 2013, the joint venture had a final investment decision in front of it and chose not to proceed. It didn’t stack up.
Woodside is still giving mixed messages. At its last Capital Markets Day, the company disclosed its assumption that Browse will not be built in either of its price scenarios. Six months later, Woodside’s CFO told a federal parliamentary inquiry: “I’m not sure about your reference to the midcase and the capital markets day, but I can say, at our midcase scenario, Browse does work...”
So why keep going?
So why would Woodside keep spruiking a project that doesn’t look like a compelling investment? I’ve got two theories.
The first is that Woodside sees Browse as an option that may become valuable in the future. But an option is only worth holding if there’s a credible price scenario in which it pays, and Woodside’s own Capital Markets Day scenarios didn’t include one.
The second is that Woodside wants to present a compelling growth story, even if it can’t see a way to deliver that growth. Investors are increasingly questioning that trade-off in public, at AGMs and in how they vote. It’s a fair question: is a longer operating life worth funding projects that fall short of the cost of capital?
LNG buyers are cutting back
The closure of the Strait of Hormuz has cut oil supply by millions of barrels a day, and the world’s second-largest LNG producer is effectively shut out of the market.
That’s good for LNG projects operating today. But it does nothing for Browse, which wouldn’t produce gas until the 2030s even if it reached a final investment decision tomorrow. By then, buyers plan to need less of it. They’re reducing their long-term exposure to LNG’s high and volatile prices and its geopolitical risk.
Europe’s electrification target is intended to reduce gas imports by 70% to “reduce dependency on imported fossil fuels” that have “repeatedly exposed our vulnerability to geopolitical shocks”. Thailand doubled its clean energy target because “the ongoing conflict in the Middle East demonstrates that we must urgently reduce imports of LNG and other fuels”.
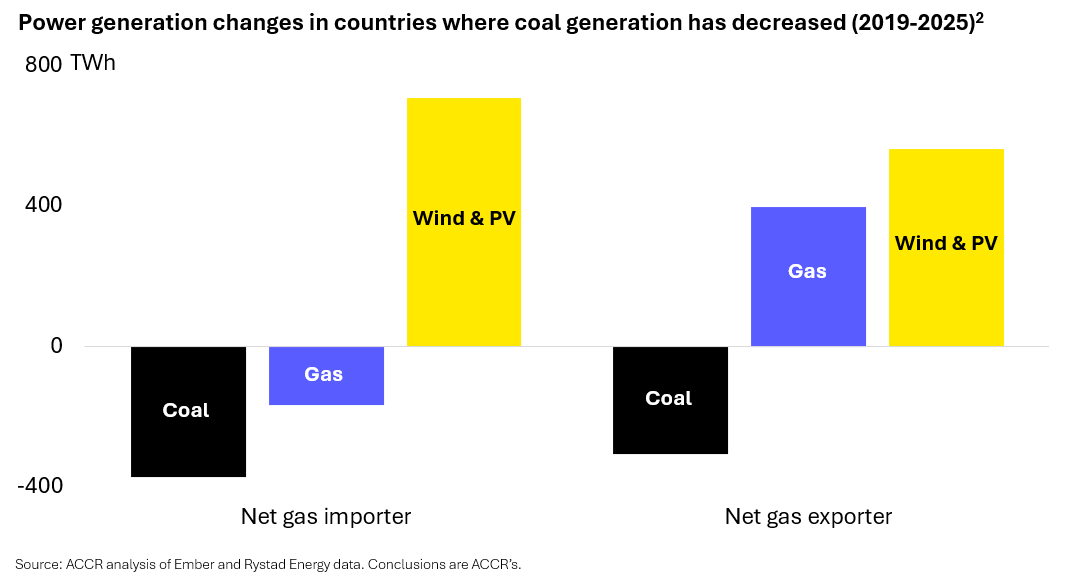
Despite Woodside’s repeated claims, LNG does not typically replace coal. Where coal generation has declined in gas-importing countries, gas generation has declined too. Replacing coal with LNG increases costs. Replacing both with renewables reduces them.
WA already has enough gas to meet domestic demand, and the North West Shelf can be backfilled without Browse. Where exporters sell their gas is a commercial decision, and it’s theirs to make. But a shortfall that exists because of that choice isn’t a reason for shareholders to fund a project priced above 70% of its global competitors.